
Thomas Crowther 🔗
Collaborating Professor
Crowther is a professor at King Abdullah University of Science and Technology. Crowther's research explores how biodiversity influences the Earth’s climate system and the wellbeing of local people who depend on it. He is particularly interested in the global distribution and functioning of plants and soil organisms (including fungi and nematodes), and how their interactions regulate global biogeochemistry. His work bridges fundamental ecology with global‐scale modeling to generate an understanding of the forces shaping biodiversity across the globe. He also focuses on how this ecological knowledge can be applied to enhance the success of conservation and restoration efforts by improving the livelihoods of local communities.

Zohner Constantin 🔗
Collaborating Professor
Constantin is a professor at University of Tokyo. Constantin’s research explores the dynamic relationship between plants and their environment, with a particular focus on addressing the challenges of climate change. His work centers around fundamental questions concerning ecosystem functioning, biodiversity, and the climate system. At the core of Constantin’s passion is the exploration of seasonal dynamics within ecosystems amidst a changing climate. Through his research, he seeks to contribute to a deeper understanding of how these ecosystems adapt and respond to environmental changes. By shedding light on the intricate interconnections between living organisms and their surroundings, he hopes to inspire actions that will safeguard and preserve our natural world for future generations.

Ruikun Gou 🔗
Associate Professor
Prof. Ruikun Gou received his Ph.D in Department of Earth System Science from Tsinghua University in 2024 and spent part of his doctoral training at ETH Zurich. His research focuses on how forests respond to climate extremes and how these responses shape ecosystem carbon and water cycling. He combines long-term field observations, eddy covariance measurements, remote sensing, and ecosystem modeling to examine changes in forest productivity, carbon uptake, and resilience under a changing climate. Through this work, he seeks to better understand the vulnerability and adaptive capacity of forest ecosystems and to inform climate adaptation and sustainable ecosystem management.
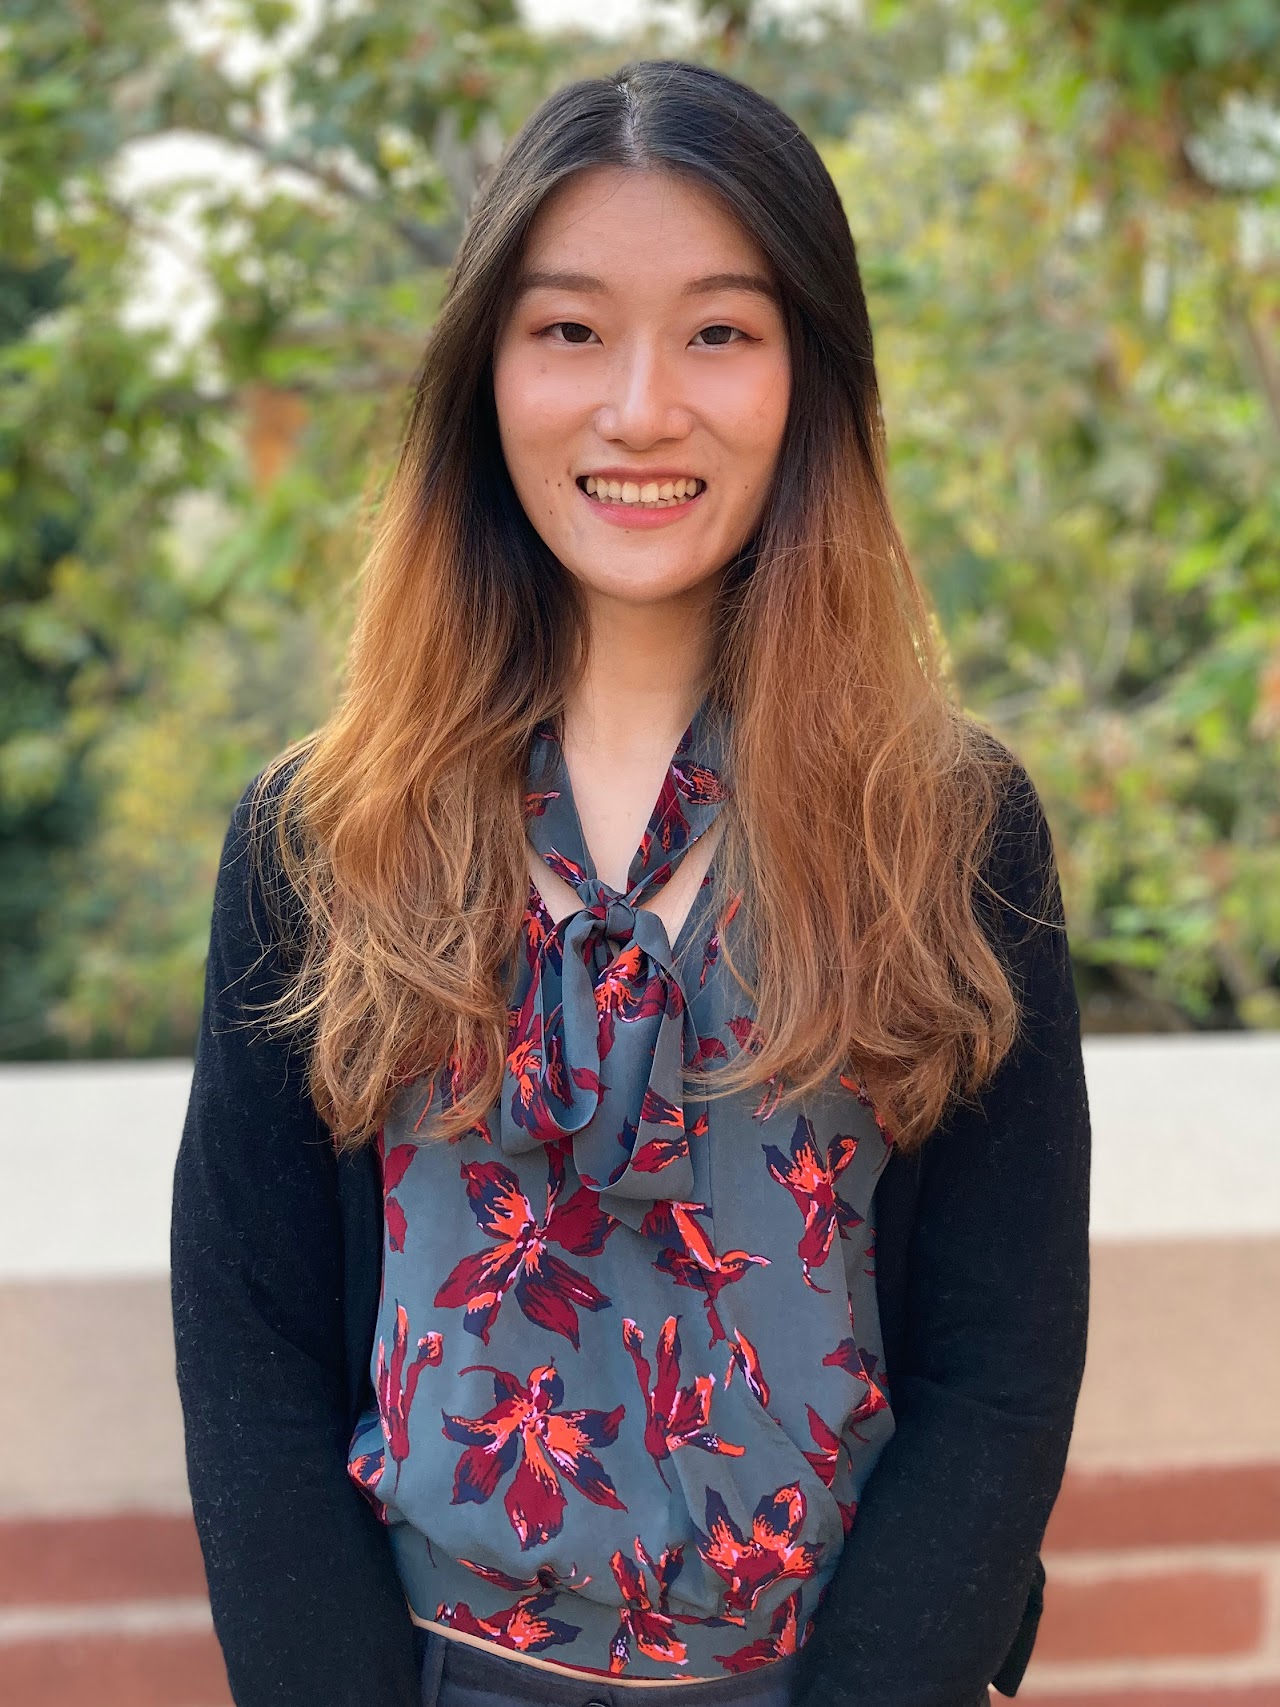
Yu Shi🔗
Associate Professor
Prof. Yu Shi's research focuses on financial economics, corporate finance, asset pricing, financial institutions, and macrofinance. Major directions include founder wealth and IPO dynamics, particularly how venture capital, ownership stakes, post-IPO liquidations, and acquisitions shape extreme wealth; informed trading and price discovery, especially insider trading around delayed reactions to public news; institutional investors and portfolio diversification, including insurance-linked securities funds, niche assets, catastrophe bonds, and dynamic risk allocation; financial firm valuation and regulation, especially decomposing life insurers’ returns into financial and business components; and capital reallocation, financial frictions, resource misallocation, and aggregate productivity. Across these areas, the work uses microdata and emphasizes information frictions, path-dependent ownership, dynamic risk-taking, and policy implications for asset prices, wealth inequality, and financial stability.